CBAM Definitive Regime Architecture from 2026 under Regulation (EU) 2023/956
Since 1 January 2026, the European Union's Carbon Border Adjustment Mechanism has operated in its full CBAM definitive regime under Regulation (EU) 2023/956 and the Omnibus I simplification package enacted by Regulation (EU) 2025/2083. The transitional reporting phase that ran from 1 October 2023 through 31 December 2025 under Implementing Regulation (EU) 2023/1773 is over. Quarterly information returns without financial settlement and without mandatory third-party verification are history. Every tonne of pig iron, crude steel, rolled profiles, tubes, fasteners, aluminium extrusions, clinker, Portland cement, ammonia, or nitrogen fertiliser cleared into the EU single market during 2026 creates a direct financial liability for the European buyer.
Ukrainian metallurgical plants, pipe mills, fastener manufacturers, cement kilns, and chemical producers felt this shift immediately in the first half of 2026. During 2024 and 2025, an EU trading house could accept a self-declared Excel CBAM Communication Template without an external assurance opinion. That practice doesn't work anymore. Under the European Commission's official CBAM rules, an EU importer must either declare physically verified Specific Embedded Emissions (SEE_g) from the actual manufacturing installation or fall back on punitive country-specific default values that strip out the exporter's price margin.
TARIC Customs Controls and Authorized CBAM Declarant Status
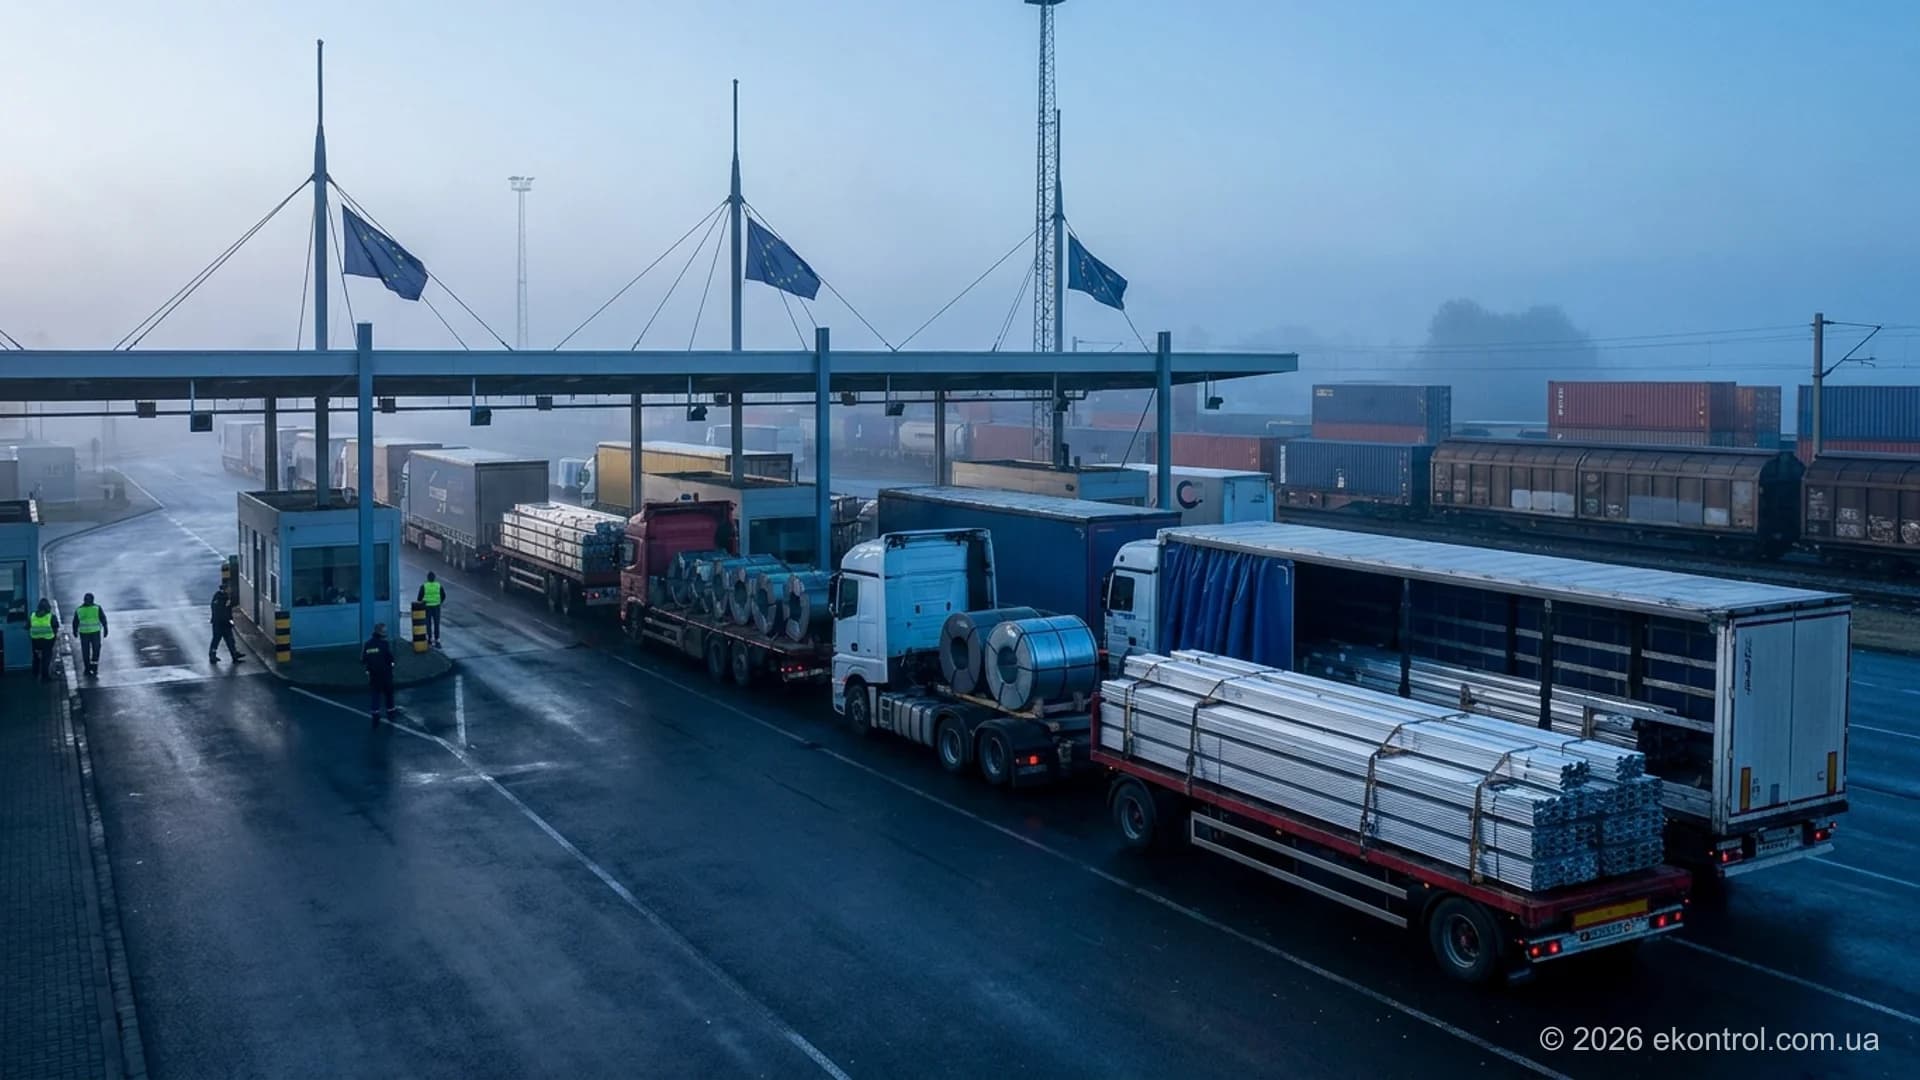
Articles 5 and 17 of Regulation (EU) 2023/956, together with Implementing Regulation (EU) 2025/486 on authorization procedures, place a strict customs filter at the external EU border. Starting 1 January 2026, release for free circulation of Annex I goods (iron and steel under CN chapters 72-73, aluminium under CN chapter 76, cement under CN heading 2523, fertilisers under CN headings 2808, 2814, 2834, and chapter 31, hydrogen under CN 2804 10 00, and electricity under CN 2716 00 00) is permitted only when the importer or indirect customs representative holds active Authorized CBAM Declarant status granted by the National Competent Authority (NCA) of their EU Member State.
Automated national customs clearance systems across all 27 Member States validate CBAM compliance in real time through dedicated TARIC document codes entered in the customs declaration:
- TARIC Code Y128: declares the importer's active Authorized CBAM Declarant account number in the central EU CBAM Registry.
- TARIC Code Y137: claims the annual de minimis mass exemption for importers whose cumulative net imports of CBAM goods stay below 50 tonnes per calendar year.
- TARIC Codes Y134, Y135, and Y136: cover specific statutory exemptions, including goods originating in EFTA countries linked to the EU ETS (Switzerland, Norway, Iceland, Liechtenstein) or military movements.
To obtain Authorized CBAM Declarant status, a European company must pass a five-year customs and tax compliance check, prove financial solvency, and demonstrate operational capacity to purchase and surrender certificates. If your buyer in Poland, Germany, Romania, or Italy crosses the 50-tonne annual threshold without an active Y128 authorization, EU customs authorities block the shipment at the border terminal.
Direct Registration of Third-Country Installations under Article 10
During the transitional period, Ukrainian exporters had to email detailed Excel spreadsheets containing fuel consumption, ferroalloy ratios, and scrap balances to every single buyer. That created a severe commercial confidentiality risk: commodity traders could reverse-engineer a plant's unit production cost from its carbon disclosure. In the definitive regime, Article 10 of Regulation (EU) 2023/956 (governed by Implementing Regulation (EU) 2024/3210) opened the Operators Portal inside the central EU CBAM Registry to third-country manufacturers.
Ukrainian operators can now register their production installations directly in the European Commission CBAM Registry, upload their Monitoring Methodology Documentation (MMD) and accredited verifier's report once per year, and selectively share only the final verified SEE_g figure per CN code with authorized EU buyers. Your commercial bill of materials stays protected inside the registry while your customers get instant regulatory proof for their annual declarations.
Core Parameters of the CBAM Definitive Regime in 2026-2027
Since 1 January 2026, financial obligations apply across 6 sectors: iron and steel, aluminium, cement, fertilisers, hydrogen, and electricity. Importers bringing in less than 50 tonnes of cumulative net mass per year are exempt. The first annual CBAM declaration and certificate surrender covering 2026 imports are due by 30 September 2027, which means continuous primary meter logging and ISO/IEC 17025 laboratory fuel testing must run throughout all of 2026.
The 50-Tonne De Minimis Threshold under Omnibus I and Exporter Supply Chain Risks
In October 2025, the European Parliament and the Council adopted Regulation (EU) 2025/2083 under the Omnibus I simplification package. This amendment repealed the transitional EUR 150 per-consignment exemption and replaced it with a cumulative 50-tonne annual net mass threshold per importer per calendar year.
The 50-tonne threshold aggregates net mass across the four mass-based industrial sectors: iron and steel, aluminium, fertilisers, and cement. It doesn't apply to electricity or hydrogen, where CBAM obligations start from the first megawatt-hour or kilogram imported. According to impact assessments published by the European Commission, this mass-based de minimis rule removes administrative obligations for roughly 182,000 small and medium-sized EU importers (around 90% of occasional declarants) while keeping more than 99% of total embedded greenhouse gas emissions inside the financial perimeter.
Why a 20-Tonne Steel Contract Does Not Guarantee a CBAM Exemption
Many mid-sized Ukrainian exporters of metal structures, fasteners, forged parts, and welded pipes make a costly mistake here. They assume that shipping 15 or 30 tonnes of steel products per year to a European client automatically exempts the transaction from CBAM. In reality, EU customs systems track the 50-tonne threshold against the European buyer's EORI number across all third-country suppliers, never per individual Ukrainian supply contract.
Consider how this plays out in a real 2026 procurement cycle:
- In March 2026, a German industrial distributor imports 18 tonnes of steel bolts and nuts (CN 7318) from your plant in Dnipro or Lviv, clearing customs under exemption code Y137.
- In June 2026, the same German distributor imports 24 tonnes of aluminium profiles (CN 7604) from a Turkish extruder.
- In October 2026, the buyer brings in 14 tonnes of drawn steel wire from India. Their cumulative annual CBAM imports hit 56 tonnes, crossing the 50.0-tonne statutory threshold.
- The moment that buyer exceeds 50 tonnes, they must hold Authorized CBAM Declarant status and report all 56 tonnes imported since 1 January 2026, including the 18 tonnes of fasteners purchased from your factory back in March.
If your plant didn't segregate natural gas and electricity consumption by production line in March, didn't collect verified precursor certificates for wire rod, and didn't contract an accredited verifier, your German buyer faces an immediate financial penalty in October. They must either surrender CBAM certificates calculated at punitive default values for your 18 tonnes and deduct that surcharge from your next invoice, or drop your factory from their approved vendor list.
Omnibus I also adjusted two financial administration rules for declarants. First, the annual deadline for filing the CBAM declaration and surrendering certificates moved from 31 May to 30 September (autumn) of the year following the import year. Second, starting in 2027, the mandatory quarterly certificate holding buffer at the end of each quarter drops from 80% to 50% of the embedded emissions imported since the beginning of the calendar year.
| Regulatory Parameter | Transitional Period (2023-2025) | Original Regulation (EU) 2023/956 Baseline | Active CBAM Definitive Regime (from 2026 with Omnibus I) |
|---|---|---|---|
| EU Customs Clearance Gate | Any EU importer or customs representative holding an EORI number | Authorized CBAM Declarant required for all shipments above EUR 150 | Authorized CBAM Declarant (TARIC code Y128) required above 50 tonnes/year |
| De Minimis Exemption Rule | Value-based: consignments with intrinsic value up to EUR 150 | Value-based: consignments up to EUR 150 | Mass-based: under 50 tonnes cumulative annual net mass (steel, aluminium, cement, fertilisers) |
| Reporting Cadence and Filing Deadline | Quarterly CBAM reports due 1 month after each quarter ends | Annual declaration and surrender due by 31 May of the following year | Annual declaration and certificate surrender due by 30 September of the following year |
| Emissions Verification (SEE_g) | Voluntary; self-calculated producer spreadsheets accepted | Mandatory verification by an accredited verifier | Mandatory physical verification under ISO 14064-3 and EU ETS rules (AVR 2018/2067) |
| Unverified Estimations and Default Values | Unlimited until Q2 2024; up to 20% estimation cap for complex goods through 2025 | Strict phase-out; default values with punitive markups | 20% estimation allowance expired; missing verification forces punitive country default values |
| CBAM Certificate Pricing Formula | Zero financial obligation (EUR 0) | Weekly average EU ETS allowance auction price from 2026 | Quarterly average EU ETS auction price in 2026; weekly average price from 2027 onward |
| Quarterly Certificate Holding Buffer | Not applicable | 80% of embedded emissions at the end of each quarter | 50% of embedded emissions at the end of each quarter starting in 2027 |
Calculating Specific Embedded Emissions (SEE_g) and Mandatory ISO 14064-3 Verification
Under the definitive regime, financial liability isn't calculated from a company's corporate-wide carbon footprint. Instead, Annex IV of Regulation (EU) 2023/956 requires calculating Specific Embedded Emissions (SEE_g) for each distinct aggregated goods category g produced within a defined physical Production Process over the calendar year. Goods are classified into simple goods (manufactured exclusively from input materials and fuels having zero embedded emissions under CBAM rules, such as iron ore, coking coal, limestone, or scrap metal) and complex goods (whose production consumes one or more CBAM precursors).
For complex goods (including rolled steel, pipes, fasteners, cement ground from purchased clinker, urea, UAN, ammonium nitrate, and wrought aluminium), the fundamental engineering equation is:
SEE_g = (AttrEm_g + EE_inp) / AL_g
Each variable in this equation must be backed by auditable primary plant records:
SEE_g(Specific Embedded Emissions): the specific embedded emissions of complex goodg, expressed in tonnes ofCO2equivalent per tonne of net product output (t CO2e / t).AttrEm_g(Attributed Emissions): the direct emissions (plus indirect emissions for cement and fertilisers; iron, steel, aluminium, and hydrogen certificate surrender currently covers direct emissions under Annex II) directly attributable to the production process of goodgduring the reporting period (t CO2e). This includes fuel combustion, process emissions from carbonate calcination or flue-gas scrubbing, and net measurable heat (Q_imp,Q_exp) and waste gas balances (blast furnace gas, coke oven gas, converter gas).AL_g(Activity Level): the total net mass in tonnes of goodgproduced by the installation during the reporting period (covering total plant output of that product category, whether exported to the EU or sold domestically).EE_inp(Embedded Emissions of Input Materials): the total embedded emissions of all CBAM precursorsiconsumed in manufacturing goodg, defined asEE_inp = sum(M_i * SEE_i), whereM_iis the mass in tonnes of precursoriused in the process andSEE_iis the verified specific embedded emissions of that precursor.
Determining installation-level direct emissions relies on three approved methodologies: the calculation-based methodology (Em = AD * EF * OF, multiplying metered Activity Data by laboratory Emission Factors and Oxidation/Conversion Factors), the mass-balance methodology (Em_MB = sum(AD_in * CC_in - AD_out * CC_out) * 3.664, mandatory for integrated steelworks, blast furnaces, basic oxygen furnaces, and ferroalloy smelting where carbon flows across ore, coke, pig iron, crude steel, and slag, with 3.664 representing the molecular-to-atomic mass ratio of CO2 to carbon 44.01 / 12.011), and the measurement-based methodology using Continuous Emission Monitoring Systems (CEMS) for stack flue gases, particularly for nitrous oxide (N2O) in nitric acid plants and perfluorocarbons (CF4 and C2F6) from anode effects in primary aluminium electrolysis.
Physical Verification Rules, the 5% Materiality Threshold, and EA / NAAU Accreditation
Under Article 8 and Annex VI of Regulation (EU) 2023/956, an Authorized CBAM Declarant can enter actual SEE_g figures in their annual declaration only if those numbers are accompanied by a satisfactory verification report. Verification follows the procedural rules of EU ETS Implementing Regulation (EU) 2018/2067 (the Accreditation and Verification Regulation, AVR) and international standard ISO 14064-3. Only verification bodies accredited to ISO/IEC 17029 and ISO 14065 by a national accreditation body belonging to European co-operation for Accreditation (EA), or operating under mutual recognition frameworks involving the National Accreditation Agency of Ukraine (NAAU), are authorized to issue CBAM verification opinions.
Chief engineers and sustainability leads at Ukrainian factories must prepare for three strict audit rules in 2026-2027:
- Mandatory On-Site Physical Inspection: in the first year of definitive regime verification, the lead verifier must physically inspect the manufacturing installation. Virtual desk reviews aren't permitted for initial verification. Auditors walk the shop floor to inspect system boundaries, gas flowmeter seals, belt weighers, transformer sub-meters, and raw shift logs.
- The 5% Materiality Threshold: a verifier cannot issue a satisfactory opinion if unadjusted misstatements, metering gaps, or unverifiable energy allocations exceed 5% of the total specific embedded emissions for a given CN product group.
- Physical Segregation of CBAM vs Non-CBAM Production: if a reheating furnace or heat-treatment line processes both Annex I CBAM steel goods and non-CBAM machinery components, allocating natural gas in proportion to financial revenue is rejected outright. Allocation must rest on sub-metering, mass throughput, or validated thermodynamic heat balances.
The 20% Unverified Estimation Allowance Expired on 31 December 2025
From July 2024 through December 2025, exporters of complex goods could estimate up to 20% of total embedded emissions (such as minor precursors) using unverified reference tables. That flexibility ended when the definitive regime took effect on 1 January 2026. If your supplier of steel billets, ferroalloys, clinker, or ammonia fails to provide an accredited verification report, or if your own plant's data fails ISO 14064-3 verification, the EU importer must apply punitive country-specific default values set by the European Commission.
CBAM Certificate Pricing, the EU ETS Benchmark Factor, and the Cost of Default Values
Each CBAM certificate corresponds to one tonne of embedded CO2e emissions (1 t CO2e). Authorized CBAM Declarants purchase certificates on the common central platform managed by the European Commission and Member States. The certificate price mirrors the allowance price in the EU Emissions Trading System (EU ETS):
- During 2026: the certificate price is calculated as the quarterly average of closing auction prices for EU ETS allowances (EUAs) in euros per tonne of
CO2e. - From 2027 onward: the price switches to the weekly average of EU ETS auction settlement prices over the preceding calendar week.
How the EU ETS Free Allocation Deduction (CBAM Factor) Works from 2026 to 2034
Because industrial installations inside the EU still receive a portion of their EU ETS allowances for free, Article 31 of Regulation (EU) 2023/956 adjusts the number of CBAM certificates surrendered by imported goods to mirror the gradual phase-out of EU free allocation. The free allocation retention factor (F_CBAM) steps down each year: 97.5% remains free in 2026 (2.5% phase-out step), 95.0% in 2027 (5% step), 90.0% in 2028 (10% step), 77.5% in 2029 (22.5% step), 51.5% in 2030 (48.5% step), reaching 0% free allocation (100% full carbon cost) in 2034.
Here's the mathematical mechanism that catches unprepared exporters off guard: in 2026, your EU buyer does not simply pay 2.5% of your plant's emissions! Instead, the payable specific embedded emissions per tonne (Payable_SEE) are calculated by subtracting the EU ETS Product Benchmark (Benchmark_ETS) multiplied by the free allocation factor F_CBAM from your product's specific embedded emissions (SEE_g):
Payable_SEE = SEE_g - (F_CBAM * Benchmark_ETS)
Let's run the exact numbers for a Ukrainian steel shipment in 2026 at an average EU ETS allowance price of EUR 75 / t CO2e:
- Case A (Exporter provides verified actual
SEE_g): suppose a Ukrainian plant produces rolled steel with verified specific embedded emissions ofSEE_g = 1.520 t CO2e/t, and the applicable combined EU ETS product benchmark isBenchmark_ETS = 1.484 t CO2e/t. In 2026, the free benchmark deduction equals0.975 * 1.484 = 1.447 t CO2e/t. The net payable emissions are just1.520 - 1.447 = 0.073 t CO2e/t. Multiplied by EUR 75, the CBAM certificate cost in 2026 is only EUR 5.48 per tonne of steel (and for an electric arc furnace mill operating at0.55 t CO2e/tagainst its EAF benchmark, the cost is close to zero). - Case B (Exporter has no verification report, forcing default values): without an ISO 14064-3 verification report, the EU declarant must use the European Commission's country default value plus punitive markup, say
2.450 t CO2e/t. After subtracting the exact same EU ETS benchmark credit (1.447 t CO2e/t), the importer must pay for the entire excess above the benchmark immediately in 2026:2.450 - 1.447 = 1.003 t CO2e/t! At EUR 75 per certificate, the CBAM tax jumps to EUR 75.23 per tonne of steel in 2026.
Losing verified actual status doesn't cost 2.5% of the carbon price; it costs nearly EUR 70 per tonne of steel right now in 2026. On a 10,000-tonne annual export contract, failing verification destroys EUR 700,000 in commercial margin.
Deducting Domestic Carbon Taxes Paid in Ukraine under Article 9
Article 9 of Regulation (EU) 2023/956 allows an Authorized CBAM Declarant to reduce the number of surrendered certificates to account for a carbon price effectively paid in the country of origin. Under the Tax Code of Ukraine, industrial operators pay a stationary-source ecological tax of 30 UAH per tonne of CO2 (roughly EUR 0.65 / t CO2). Claiming even this minor deduction requires certified tax returns, treasury payment receipts proving no rebates were granted, and a verified allocation of paid tax per tonne of product g. Because EUR 0.65 offsets less than 1% of a EUR 75 EU ETS allowance price, a Ukrainian exporter's only real financial shield prior to the launch of a harmonized Ukrainian national ETS is proving low actual SEE_g through accredited verification.
| Industrial Sector and CN Codes (Annex I) | Verified Actual SEE_g (t CO2e/t) | Unverified Default Value + Markup (t CO2e/t) | 2026 Payable Emissions after 97.5% EU ETS Benchmark Credit (t CO2e/t) | 2026 CBAM Certificate Cost at EUR 75/t CO2e (EUR per tonne of product) |
|---|---|---|---|---|
| Electric Arc Furnace Steel (EAF): billets, wire rod, rebar (CN 7207, 7213, 7214) | 0.45 - 0.68 (direct emissions driven by high scrap charge) | 1.15 - 1.45 (punitive default route without verified technology proof) | Verified: 0.05 - 0.18 | Default: 0.84 - 1.14 | Verified: EUR 3.75 - 13.50/t | Default: EUR 63.00 - 85.50/t |
| Integrated Steel Route (BF-BOF): pig iron, slabs, hot-rolled coil (CN 7201, 7208) | 1.82 - 2.08 (with verified blast-furnace and coke-oven gas balances) | 2.45 - 2.85 (country default value with progressive markup factor) | Verified: 0.37 - 0.63 | Default: 1.00 - 1.40 | Verified: EUR 27.75 - 47.25/t | Default: EUR 75.00 - 105.00/t |
| Cement Sector: grey clinker and Portland cement (CN 2523 10 00, 2523 29 00) | 0.62 - 0.78 (accounting for mineral clinker substitutes and biomass) | 0.96 - 1.18 (default value when ISO/IEC 17025 carbonate tests are missing) | Verified: 0.04 - 0.12 | Default: 0.29 - 0.51 | Verified: EUR 3.00 - 9.00/t | Default: EUR 21.75 - 38.25/t |
| Nitrogen Fertilisers: anhydrous ammonia, urea, UAN, ammonium nitrate (CN 2814, 3102) | 1.55 - 2.05 (with catalytic N2O abatement and CEMS stack monitoring) | 2.60 - 3.25 (punitive default without verified N2O CEMS records) | Verified: 0.11 - 0.38 | Default: 1.05 - 1.70 | Verified: EUR 8.25 - 28.50/t | Default: EUR 78.75 - 127.50/t |
Protect Your EU Export Contracts from Punitive CBAM Default Values
Ekontrol engineers and lead auditors evaluate your installation's emissions accounting, build audit-proof data control systems under ISO 14001 and ISO 50001, and prepare Ukrainian manufacturers for physical CBAM verification.
Request a CBAM Diagnostic Audit with EkontrolIntegration with Ukrainian MRV Law No. 377-IX and ISO/IEC 17025 Laboratory Testing
Many large Ukrainian industrial installations already operate an approved Monitoring Plan under Law of Ukraine No. 377-IX 'On Principles of Monitoring, Reporting and Verification of Greenhouse Gas Emissions' and Cabinet of Ministers Resolutions No. 960 and No. 880, or compile corporate carbon inventories under the GHG Protocol Corporate Standard (Scope 1, Scope 2, and Scope 3). Existing national MRV documentation gives a plant roughly 65% to 70% of the primary evidence required for CBAM, but the remaining 30% to 35% structural gap regularly causes EU verifiers to reject uncorrected national reports.
The core engineering divergence comes down to system boundaries:
- Ukrainian National MRV (Law No. 377-IX) and ISO 14064-1 measure total direct emissions across the entire stationary installation boundary (boilers, furnaces, kilns, flares) as a single annual sum, without splitting fuel flows by finished product SKU and without tracking embedded emissions of purchased precursors (
EE_inp). - EU CBAM (Regulation (EU) 2023/956) requires carving the facility into discrete Production Processes tied to Annex I CN codes, stripping out energy consumed by non-CBAM workshops, calculating measurable heat transfers (
Q_imp,Q_exp) and waste gases between units, recording indirect electricity emissions, and adding the verified specific embedded emissions of every tonne of input precursor consumed.
Why CBAM Verifiers Reject Emission Factors Without ISO/IEC 17025 Laboratory Protocols
When a Ukrainian manufacturer applies the calculation-based or mass-balance methodology to prove low actual emissions, its formulas depend on physical and chemical parameters of fuels and raw materials: Net Calorific Value (NCV) and carbon content (CC) of coal, coke, natural gas, scrap, graphite electrodes, and ferroalloys, or calcium and magnesium carbonate content (CaCO3, MgCO3) in limestone, dolomite, and clay, plus free CaO in clinker.
Under Annex IV of Regulation (EU) 2023/956 and EU ETS monitoring rules, an operator may use plant-specific calculation factors (rather than conservative upper-bound IPCC default factors) only when sampling and chemical analyses are executed by testing laboratories accredited to ISO/IEC 17025 by the National Accreditation Agency of Ukraine (NAAU) or an accreditation body signatory to the European co-operation for Accreditation (EA) MLA.
During the physical site audit, the CBAM verifier inspects four metrological and laboratory pillars:
- ISO/IEC 17025 Accreditation Scope: your in-house factory lab or external contract laboratory must hold a valid ISO/IEC 17025 accreditation certificate covering the exact test standards (EN, ISO, ASTM, or harmonized DSTU methods) used to determine carbon content, ash, moisture, and calorific value for each batch.
- Documented Sampling Plans and Retained Samples: sampling from railcars, auger samplers, or conveyor belts must follow a written procedure that eliminates bias and preserves sealed reference samples.
- Metrological Calibration of Weighing and Flow Instruments: custody-transfer and internal rotary/ultrasonic gas flowmeters, hopper scales, belt weighers, truck scales, and CEMS analyzers must hold valid calibration certificates issued by ISO/IEC 17025 calibration laboratories, demonstrating a combined measurement uncertainty below the required tier threshold (
1.5%to2.5%). - Biomass Zero-Rating Proof under ISCC: if a cement kiln, dryer, or boiler co-fires solid biomass (sunflower husk pellets, wood chips, biomethane, or biogenic RDF fractions) to claim a zero emission factor (
EF_bio = 0), the fuel must satisfy RED III sustainability and greenhouse gas saving criteria verified through ISCC certification, backed by14Cbiogenic carbon fraction testing (EN ISO 21644). Without valid sustainability proof, the verifier must count 100% of the biomass carbon as fossil fuel!
Building an Audit-Proof CBAM Data Control System with ISO 14001, ISO 50001, and ISO 9001
A major surprise for exporters during their first physical CBAM verification is that the auditor checks far more than arithmetic formulas. Under ISO 14064-3 and the EU ETS Verification Regulation, the verifier must audit the operator's Data Flow Activities and Control System (risk assessment of inherent and control risks, four-eyes review, IT/ERP data integrity, and missing-data fallback procedures). When a plant relies on a standalone spreadsheet edited manually by one environmental engineer without automated reconciliation against SAP/ERP warehouse ledgers and metrological logs, the verifier classifies Control Risk as high and cannot issue an unqualified verification opinion.
Integrating three international management system standards gives Ukrainian manufacturers an auditable governance structure that satisfies both accredited CBAM verifiers and EU corporate procurement audits:
- Environmental Management System (ISO 14001): establishes organizational accountability, the register of environmental aspects and stationary emission sources, standard operating procedures for closing metering data gaps when a flowmeter or CEMS unit goes offline, internal CBAM audit schedules, and Corrective and Preventive Action (CAPA) logs.
- Energy Management System (ISO 50001): solves the hardest engineering problem in CBAM attribution, namely splitting natural gas, coal, steam, and electricity consumption across distinct production processes. Clause 6 of ISO 50001 requires identifying Significant Energy Uses (SEUs), installing line-level sub-metering, and maintaining normalized Energy Baselines (EnB), which map directly into the plant's CBAM Monitoring Methodology Documentation (MMD).
- Quality Management System (ISO 9001): governs batch identification and traceability across the supply chain (Clause 8.5.2) and control of monitoring and measuring resources (Clause 7.1.5). Embedding CBAM data requirements into ISO 9001 incoming inspection procedures forces procurement teams to collect verified precursor
SEE_ideclarations alongside mill test certificates for every incoming shipment.
Precursor Traceability (EE_inp) Across Steel, Aluminium, Cement, and Fertilisers
For downstream and midstream processors (such as hot-rolled and welded pipe mills, wire-drawing plants, fastener factories, cold-rolling mills, cement grinding plants, and complex NPK fertiliser blenders), direct on-site fuel combustion (AttrEm_g) typically accounts for only 8% to 18% of total product emissions. The remaining 82% to 92% comes from EE_inp: the embedded emissions of purchased steel billets, wire rod, hot-rolled coils, clinker, ammonia, or nitric acid.
Without batch-level traceability under ISO 9001 linking each export lot shipped to Germany or Poland back to a specific supplier heat number and its verified SEE_i report, a verifier cannot allow you to claim low-carbon precursor inputs. If EAF steel billets (0.52 t CO2e/t) and blast-furnace billets (1.98 t CO2e/t) sit in the same yard without ERP lot segregation, the auditor is legally required to apply the highest emission factor or punitive default value across the entire production run.
| CBAM Verification Requirement (Regulation (EU) 2023/956) | Primary Engineering and Accounting Evidence at the Plant | Supporting Management Standard and Clause | Typical Audit Nonconformity When Missing |
|---|---|---|---|
| Installation and Production Process Boundaries (Annex IV) | Site plan, PFD/P&ID process flow diagrams, source stream list, CN code mapping | ISO 14001 (Clauses 4.3, 6.1.2) + National MRV Monitoring Plan (Law No. 377-IX) | Including administrative heating boilers or non-CBAM machining shops inside SEE_g |
| Fuel, Measurable Heat, and Electricity Attribution (AttrEm_g) | Line-level gas, steam, and kWh sub-meters, validated enthalpy heat balances | ISO 50001 (Clause 6.3 energy review of SEUs, Clause 6.6 energy data collection plan) | Prorating the plant-wide utility gas invoice by product revenue or rough tonnage |
| Metrological Validity of Activity Data (AD) | Calibration certificates for scales and flowmeters, tier uncertainty < 1.5-2.5% | ISO 9001 (Clause 7.1.5) + ISO/IEC 17025 accredited calibration laboratories (NAAU) | Expired calibration on rotary gas meters, hopper scales, or conveyor belt weighers |
| Laboratory Proof of Calculation Factors (EF, NCV, CC, OF) | Chemical test reports for coal, coke, limestone, scrap, electrodes, ferroalloys | Testing laboratories accredited to ISO/IEC 17025 (EA MLA / NAAU) | Relying on unaccredited internal lab checks without validated sampling protocols |
| Zero-Rating of Biogenic Fuels (EF_bio = 0) | Biomass mass balance, RED III sustainability certificates, 14C fraction analysis | ISCC EU supply chain certification + ISO/IEC 17025 laboratory testing | Unverified sunflower husk pellets or wood chips treated as 100% fossil carbon |
| Precursor Batch Traceability (EE_inp) | ERP lot tracking linking supplier heat numbers and SEE_i to exported batches | ISO 9001 (Clause 8.4 supplier control, Clause 8.5.2 identification and traceability) | Commingled raw material stock; verifier forces worst-case default on all output |
| Data Flow Activities and Internal Control System (Annex VI) | Data risk matrix, four-eyes ERP reconciliation, missing-data substitution SOP | ISO 14001 (Clause 9.1 monitoring, Clause 9.2 internal audit, Clause 10.2 CAPA) | Unprotected single-user Excel file with manual overrides and no audit trail |
Engineering Synergy of ISO 14001, ISO 50001, and ISO/IEC 17025
Across Ekontrol industrial projects, manufacturers that align their Law No. 377-IX MRV Monitoring Plan with ISO 14001 data controls, ISO 50001 sub-metering, and ISO/IEC 17025 accredited laboratories cut on-site CBAM verification time by 40% to 50%. This integrated architecture protects export contracts against punitive default value markups while satisfying ESG due diligence from European lenders and OEM buyers.
Step-by-Step Engineering Roadmap for CBAM Verification Readiness with Ekontrol
Beyond the six initial sectors, on 12 June 2026 the Council of the EU approved a negotiating mandate to extend CBAM to additional downstream steel and aluminium products and tighten anti-circumvention enforcement. Manufacturers of fabricated metal goods, machinery components, and wire products sitting right outside Annex I today must build product-level carbon accounting before downstream CN codes are locked in.
To pass physical verification for the 2026 reporting year and deliver legally defensible SEE_g reports to European buyers ahead of the 2027 declaration window, the engineering and audit team at Ekontrol recommends executing a structured six-stage roadmap:
- Engineering Diagnostic of CN Codes, Process Boundaries, and Buyer Thresholds (diagnostic audit): map every exported product against Annex I of Regulation (EU) 2023/956, classify simple versus complex goods, verify your EU buyers' cumulative annual import volumes against the 50-tonne de minimis limit, and confirm their Authorized CBAM Declarant status (TARIC code Y128).
- Energy Flow Segregation and Metrological Audit (ISO 50001 and ISO 9001): isolate natural gas, coal, steam, and electricity consumption for CBAM production processes from non-CBAM workshops and space heating. Audit calibration intervals and uncertainty calculations for all gas correctors, scales, and CEMS analyzers.
- Transitioning Fuel and Raw Material Testing to ISO/IEC 17025 Laboratories: route calorific value, carbon content, and carbonate purity testing for coal, coke, ferroalloys, limestone, and clinker to laboratories accredited by NAAU, or prepare your in-house factory lab for ISO/IEC 17025 accreditation. Where solid biomass is co-fired, establish ISCC chain-of-custody certification.
- Authoring the Monitoring Methodology Documentation (MMD) and Data Control System (management system implementation): codify the mathematical formulas for
SEE_g, configure ERP batch traceability for precursor inputsEE_inpunder ISO 9001, and implement data risk controls and missing-data procedures within your ISO 14001 environmental management system. - Article 10 CBAM Registry Registration and Pre-Verification Mock Audit (audit support): register your installations in the European Commission's Operators Portal, collect verified precursor passports from upstream suppliers, and execute a full internal mock verification against the 5% materiality threshold under ISO 14064-3.
- On-Site Accredited Verification Support and Contract Integration: host the accredited verifier's physical site inspection, secure the satisfactory verification opinion, and lock verified
SEE_gclauses into your 2027 EU supply contracts.
Don't wait until an EU buyer applies punitive default values and deducts EUR 60 to EUR 90 per tonne from your contract price. Contact the Ekontrol engineering team to schedule a CBAM readiness diagnostic, align your ISO/IEC 17025 laboratory protocols, and build a certified ISO 14001 and ISO 50001 data control system.
Need a certification consultation?
Free ConsultationOn This Page
- CBAM Definitive Regime Architecture from 2026 under Regulation (EU) 2023/956
- The 50-Tonne De Minimis Threshold under Omnibus I and Exporter Supply Chain Risks
- Calculating Specific Embedded Emissions (SEE_g) and Mandatory ISO 14064-3 Verification
- CBAM Certificate Pricing, the EU ETS Benchmark Factor, and the Cost of Default Values
- Integration with Ukrainian MRV Law No. 377-IX and ISO/IEC 17025 Laboratory Testing
- Building an Audit-Proof CBAM Data Control System with ISO 14001, ISO 50001, and ISO 9001
- Step-by-Step Engineering Roadmap for CBAM Verification Readiness with Ekontrol
- FAQ: CBAM Definitive Regime, SEE Verification, and Certificates Explained
CBAM Definitive Regime Architecture from 2026 under Regulation (EU) 2023/956
Since 1 January 2026, the European Union's Carbon Border Adjustment Mechanism has operated in its full CBAM definitive regime under Regulation (EU) 2023/956 and the Omnibus I simplification package enacted by Regulation (EU) 2025/2083. The transitional reporting phase that ran from 1 October 2023 through 31 December 2025 under Implementing Regulation (EU) 2023/1773 is over. Quarterly information returns without financial settlement and without mandatory third-party verification are history. Every tonne of pig iron, crude steel, rolled profiles, tubes, fasteners, aluminium extrusions, clinker, Portland cement, ammonia, or nitrogen fertiliser cleared into the EU single market during 2026 creates a direct financial liability for the European buyer.
Ukrainian metallurgical plants, pipe mills, fastener manufacturers, cement kilns, and chemical producers felt this shift immediately in the first half of 2026. During 2024 and 2025, an EU trading house could accept a self-declared Excel CBAM Communication Template without an external assurance opinion. That practice doesn't work anymore. Under the European Commission's official CBAM rules, an EU importer must either declare physically verified Specific Embedded Emissions (SEE_g) from the actual manufacturing installation or fall back on punitive country-specific default values that strip out the exporter's price margin.
TARIC Customs Controls and Authorized CBAM Declarant Status
Articles 5 and 17 of Regulation (EU) 2023/956, together with Implementing Regulation (EU) 2025/486 on authorization procedures, place a strict customs filter at the external EU border. Starting 1 January 2026, release for free circulation of Annex I goods (iron and steel under CN chapters 72-73, aluminium under CN chapter 76, cement under CN heading 2523, fertilisers under CN headings 2808, 2814, 2834, and chapter 31, hydrogen under CN 2804 10 00, and electricity under CN 2716 00 00) is permitted only when the importer or indirect customs representative holds active Authorized CBAM Declarant status granted by the National Competent Authority (NCA) of their EU Member State.
Automated national customs clearance systems across all 27 Member States validate CBAM compliance in real time through dedicated TARIC document codes entered in the customs declaration:
- TARIC Code Y128: declares the importer's active Authorized CBAM Declarant account number in the central EU CBAM Registry.
- TARIC Code Y137: claims the annual de minimis mass exemption for importers whose cumulative net imports of CBAM goods stay below 50 tonnes per calendar year.
- TARIC Codes Y134, Y135, and Y136: cover specific statutory exemptions, including goods originating in EFTA countries linked to the EU ETS (Switzerland, Norway, Iceland, Liechtenstein) or military movements.
To obtain Authorized CBAM Declarant status, a European company must pass a five-year customs and tax compliance check, prove financial solvency, and demonstrate operational capacity to purchase and surrender certificates. If your buyer in Poland, Germany, Romania, or Italy crosses the 50-tonne annual threshold without an active Y128 authorization, EU customs authorities block the shipment at the border terminal.
Direct Registration of Third-Country Installations under Article 10
During the transitional period, Ukrainian exporters had to email detailed Excel spreadsheets containing fuel consumption, ferroalloy ratios, and scrap balances to every single buyer. That created a severe commercial confidentiality risk: commodity traders could reverse-engineer a plant's unit production cost from its carbon disclosure. In the definitive regime, Article 10 of Regulation (EU) 2023/956 (governed by Implementing Regulation (EU) 2024/3210) opened the Operators Portal inside the central EU CBAM Registry to third-country manufacturers.
Ukrainian operators can now register their production installations directly in the European Commission CBAM Registry, upload their Monitoring Methodology Documentation (MMD) and accredited verifier's report once per year, and selectively share only the final verified SEE_g figure per CN code with authorized EU buyers. Your commercial bill of materials stays protected inside the registry while your customers get instant regulatory proof for their annual declarations.
Core Parameters of the CBAM Definitive Regime in 2026-2027
Since 1 January 2026, financial obligations apply across 6 sectors: iron and steel, aluminium, cement, fertilisers, hydrogen, and electricity. Importers bringing in less than 50 tonnes of cumulative net mass per year are exempt. The first annual CBAM declaration and certificate surrender covering 2026 imports are due by 30 September 2027, which means continuous primary meter logging and ISO/IEC 17025 laboratory fuel testing must run throughout all of 2026.
The 50-Tonne De Minimis Threshold under Omnibus I and Exporter Supply Chain Risks
In October 2025, the European Parliament and the Council adopted Regulation (EU) 2025/2083 under the Omnibus I simplification package. This amendment repealed the transitional EUR 150 per-consignment exemption and replaced it with a cumulative 50-tonne annual net mass threshold per importer per calendar year.
The 50-tonne threshold aggregates net mass across the four mass-based industrial sectors: iron and steel, aluminium, fertilisers, and cement. It doesn't apply to electricity or hydrogen, where CBAM obligations start from the first megawatt-hour or kilogram imported. According to impact assessments published by the European Commission, this mass-based de minimis rule removes administrative obligations for roughly 182,000 small and medium-sized EU importers (around 90% of occasional declarants) while keeping more than 99% of total embedded greenhouse gas emissions inside the financial perimeter.
Why a 20-Tonne Steel Contract Does Not Guarantee a CBAM Exemption
Many mid-sized Ukrainian exporters of metal structures, fasteners, forged parts, and welded pipes make a costly mistake here. They assume that shipping 15 or 30 tonnes of steel products per year to a European client automatically exempts the transaction from CBAM. In reality, EU customs systems track the 50-tonne threshold against the European buyer's EORI number across all third-country suppliers, never per individual Ukrainian supply contract.
Consider how this plays out in a real 2026 procurement cycle:
- In March 2026, a German industrial distributor imports 18 tonnes of steel bolts and nuts (CN 7318) from your plant in Dnipro or Lviv, clearing customs under exemption code Y137.
- In June 2026, the same German distributor imports 24 tonnes of aluminium profiles (CN 7604) from a Turkish extruder.
- In October 2026, the buyer brings in 14 tonnes of drawn steel wire from India. Their cumulative annual CBAM imports hit 56 tonnes, crossing the 50.0-tonne statutory threshold.
- The moment that buyer exceeds 50 tonnes, they must hold Authorized CBAM Declarant status and report all 56 tonnes imported since 1 January 2026, including the 18 tonnes of fasteners purchased from your factory back in March.
If your plant didn't segregate natural gas and electricity consumption by production line in March, didn't collect verified precursor certificates for wire rod, and didn't contract an accredited verifier, your German buyer faces an immediate financial penalty in October. They must either surrender CBAM certificates calculated at punitive default values for your 18 tonnes and deduct that surcharge from your next invoice, or drop your factory from their approved vendor list.
Omnibus I also adjusted two financial administration rules for declarants. First, the annual deadline for filing the CBAM declaration and surrendering certificates moved from 31 May to 30 September (autumn) of the year following the import year. Second, starting in 2027, the mandatory quarterly certificate holding buffer at the end of each quarter drops from 80% to 50% of the embedded emissions imported since the beginning of the calendar year.
| Regulatory Parameter | Transitional Period (2023-2025) | Original Regulation (EU) 2023/956 Baseline | Active CBAM Definitive Regime (from 2026 with Omnibus I) |
|---|---|---|---|
| EU Customs Clearance Gate | Any EU importer or customs representative holding an EORI number | Authorized CBAM Declarant required for all shipments above EUR 150 | Authorized CBAM Declarant (TARIC code Y128) required above 50 tonnes/year |
| De Minimis Exemption Rule | Value-based: consignments with intrinsic value up to EUR 150 | Value-based: consignments up to EUR 150 | Mass-based: under 50 tonnes cumulative annual net mass (steel, aluminium, cement, fertilisers) |
| Reporting Cadence and Filing Deadline | Quarterly CBAM reports due 1 month after each quarter ends | Annual declaration and surrender due by 31 May of the following year | Annual declaration and certificate surrender due by 30 September of the following year |
| Emissions Verification (SEE_g) | Voluntary; self-calculated producer spreadsheets accepted | Mandatory verification by an accredited verifier | Mandatory physical verification under ISO 14064-3 and EU ETS rules (AVR 2018/2067) |
| Unverified Estimations and Default Values | Unlimited until Q2 2024; up to 20% estimation cap for complex goods through 2025 | Strict phase-out; default values with punitive markups | 20% estimation allowance expired; missing verification forces punitive country default values |
| CBAM Certificate Pricing Formula | Zero financial obligation (EUR 0) | Weekly average EU ETS allowance auction price from 2026 | Quarterly average EU ETS auction price in 2026; weekly average price from 2027 onward |
| Quarterly Certificate Holding Buffer | Not applicable | 80% of embedded emissions at the end of each quarter | 50% of embedded emissions at the end of each quarter starting in 2027 |
Calculating Specific Embedded Emissions (SEE_g) and Mandatory ISO 14064-3 Verification
Under the definitive regime, financial liability isn't calculated from a company's corporate-wide carbon footprint. Instead, Annex IV of Regulation (EU) 2023/956 requires calculating Specific Embedded Emissions (SEE_g) for each distinct aggregated goods category g produced within a defined physical Production Process over the calendar year. Goods are classified into simple goods (manufactured exclusively from input materials and fuels having zero embedded emissions under CBAM rules, such as iron ore, coking coal, limestone, or scrap metal) and complex goods (whose production consumes one or more CBAM precursors).
For complex goods (including rolled steel, pipes, fasteners, cement ground from purchased clinker, urea, UAN, ammonium nitrate, and wrought aluminium), the fundamental engineering equation is:
SEE_g = (AttrEm_g + EE_inp) / AL_g
Each variable in this equation must be backed by auditable primary plant records:
SEE_g(Specific Embedded Emissions): the specific embedded emissions of complex goodg, expressed in tonnes ofCO2equivalent per tonne of net product output (t CO2e / t).AttrEm_g(Attributed Emissions): the direct emissions (plus indirect emissions for cement and fertilisers; iron, steel, aluminium, and hydrogen certificate surrender currently covers direct emissions under Annex II) directly attributable to the production process of goodgduring the reporting period (t CO2e). This includes fuel combustion, process emissions from carbonate calcination or flue-gas scrubbing, and net measurable heat (Q_imp,Q_exp) and waste gas balances (blast furnace gas, coke oven gas, converter gas).AL_g(Activity Level): the total net mass in tonnes of goodgproduced by the installation during the reporting period (covering total plant output of that product category, whether exported to the EU or sold domestically).EE_inp(Embedded Emissions of Input Materials): the total embedded emissions of all CBAM precursorsiconsumed in manufacturing goodg, defined asEE_inp = sum(M_i * SEE_i), whereM_iis the mass in tonnes of precursoriused in the process andSEE_iis the verified specific embedded emissions of that precursor.
Determining installation-level direct emissions relies on three approved methodologies: the calculation-based methodology (Em = AD * EF * OF, multiplying metered Activity Data by laboratory Emission Factors and Oxidation/Conversion Factors), the mass-balance methodology (Em_MB = sum(AD_in * CC_in - AD_out * CC_out) * 3.664, mandatory for integrated steelworks, blast furnaces, basic oxygen furnaces, and ferroalloy smelting where carbon flows across ore, coke, pig iron, crude steel, and slag, with 3.664 representing the molecular-to-atomic mass ratio of CO2 to carbon 44.01 / 12.011), and the measurement-based methodology using Continuous Emission Monitoring Systems (CEMS) for stack flue gases, particularly for nitrous oxide (N2O) in nitric acid plants and perfluorocarbons (CF4 and C2F6) from anode effects in primary aluminium electrolysis.
Physical Verification Rules, the 5% Materiality Threshold, and EA / NAAU Accreditation
Under Article 8 and Annex VI of Regulation (EU) 2023/956, an Authorized CBAM Declarant can enter actual SEE_g figures in their annual declaration only if those numbers are accompanied by a satisfactory verification report. Verification follows the procedural rules of EU ETS Implementing Regulation (EU) 2018/2067 (the Accreditation and Verification Regulation, AVR) and international standard ISO 14064-3. Only verification bodies accredited to ISO/IEC 17029 and ISO 14065 by a national accreditation body belonging to European co-operation for Accreditation (EA), or operating under mutual recognition frameworks involving the National Accreditation Agency of Ukraine (NAAU), are authorized to issue CBAM verification opinions.
Chief engineers and sustainability leads at Ukrainian factories must prepare for three strict audit rules in 2026-2027:
- Mandatory On-Site Physical Inspection: in the first year of definitive regime verification, the lead verifier must physically inspect the manufacturing installation. Virtual desk reviews aren't permitted for initial verification. Auditors walk the shop floor to inspect system boundaries, gas flowmeter seals, belt weighers, transformer sub-meters, and raw shift logs.
- The 5% Materiality Threshold: a verifier cannot issue a satisfactory opinion if unadjusted misstatements, metering gaps, or unverifiable energy allocations exceed 5% of the total specific embedded emissions for a given CN product group.
- Physical Segregation of CBAM vs Non-CBAM Production: if a reheating furnace or heat-treatment line processes both Annex I CBAM steel goods and non-CBAM machinery components, allocating natural gas in proportion to financial revenue is rejected outright. Allocation must rest on sub-metering, mass throughput, or validated thermodynamic heat balances.
The 20% Unverified Estimation Allowance Expired on 31 December 2025
From July 2024 through December 2025, exporters of complex goods could estimate up to 20% of total embedded emissions (such as minor precursors) using unverified reference tables. That flexibility ended when the definitive regime took effect on 1 January 2026. If your supplier of steel billets, ferroalloys, clinker, or ammonia fails to provide an accredited verification report, or if your own plant's data fails ISO 14064-3 verification, the EU importer must apply punitive country-specific default values set by the European Commission.
CBAM Certificate Pricing, the EU ETS Benchmark Factor, and the Cost of Default Values
Each CBAM certificate corresponds to one tonne of embedded CO2e emissions (1 t CO2e). Authorized CBAM Declarants purchase certificates on the common central platform managed by the European Commission and Member States. The certificate price mirrors the allowance price in the EU Emissions Trading System (EU ETS):
- During 2026: the certificate price is calculated as the quarterly average of closing auction prices for EU ETS allowances (EUAs) in euros per tonne of
CO2e. - From 2027 onward: the price switches to the weekly average of EU ETS auction settlement prices over the preceding calendar week.
How the EU ETS Free Allocation Deduction (CBAM Factor) Works from 2026 to 2034
Because industrial installations inside the EU still receive a portion of their EU ETS allowances for free, Article 31 of Regulation (EU) 2023/956 adjusts the number of CBAM certificates surrendered by imported goods to mirror the gradual phase-out of EU free allocation. The free allocation retention factor (F_CBAM) steps down each year: 97.5% remains free in 2026 (2.5% phase-out step), 95.0% in 2027 (5% step), 90.0% in 2028 (10% step), 77.5% in 2029 (22.5% step), 51.5% in 2030 (48.5% step), reaching 0% free allocation (100% full carbon cost) in 2034.
Here's the mathematical mechanism that catches unprepared exporters off guard: in 2026, your EU buyer does not simply pay 2.5% of your plant's emissions! Instead, the payable specific embedded emissions per tonne (Payable_SEE) are calculated by subtracting the EU ETS Product Benchmark (Benchmark_ETS) multiplied by the free allocation factor F_CBAM from your product's specific embedded emissions (SEE_g):
Payable_SEE = SEE_g - (F_CBAM * Benchmark_ETS)
Let's run the exact numbers for a Ukrainian steel shipment in 2026 at an average EU ETS allowance price of EUR 75 / t CO2e:
- Case A (Exporter provides verified actual
SEE_g): suppose a Ukrainian plant produces rolled steel with verified specific embedded emissions ofSEE_g = 1.520 t CO2e/t, and the applicable combined EU ETS product benchmark isBenchmark_ETS = 1.484 t CO2e/t. In 2026, the free benchmark deduction equals0.975 * 1.484 = 1.447 t CO2e/t. The net payable emissions are just1.520 - 1.447 = 0.073 t CO2e/t. Multiplied by EUR 75, the CBAM certificate cost in 2026 is only EUR 5.48 per tonne of steel (and for an electric arc furnace mill operating at0.55 t CO2e/tagainst its EAF benchmark, the cost is close to zero). - Case B (Exporter has no verification report, forcing default values): without an ISO 14064-3 verification report, the EU declarant must use the European Commission's country default value plus punitive markup, say
2.450 t CO2e/t. After subtracting the exact same EU ETS benchmark credit (1.447 t CO2e/t), the importer must pay for the entire excess above the benchmark immediately in 2026:2.450 - 1.447 = 1.003 t CO2e/t! At EUR 75 per certificate, the CBAM tax jumps to EUR 75.23 per tonne of steel in 2026.
Losing verified actual status doesn't cost 2.5% of the carbon price; it costs nearly EUR 70 per tonne of steel right now in 2026. On a 10,000-tonne annual export contract, failing verification destroys EUR 700,000 in commercial margin.
Deducting Domestic Carbon Taxes Paid in Ukraine under Article 9
Article 9 of Regulation (EU) 2023/956 allows an Authorized CBAM Declarant to reduce the number of surrendered certificates to account for a carbon price effectively paid in the country of origin. Under the Tax Code of Ukraine, industrial operators pay a stationary-source ecological tax of 30 UAH per tonne of CO2 (roughly EUR 0.65 / t CO2). Claiming even this minor deduction requires certified tax returns, treasury payment receipts proving no rebates were granted, and a verified allocation of paid tax per tonne of product g. Because EUR 0.65 offsets less than 1% of a EUR 75 EU ETS allowance price, a Ukrainian exporter's only real financial shield prior to the launch of a harmonized Ukrainian national ETS is proving low actual SEE_g through accredited verification.
| Industrial Sector and CN Codes (Annex I) | Verified Actual SEE_g (t CO2e/t) | Unverified Default Value + Markup (t CO2e/t) | 2026 Payable Emissions after 97.5% EU ETS Benchmark Credit (t CO2e/t) | 2026 CBAM Certificate Cost at EUR 75/t CO2e (EUR per tonne of product) |
|---|---|---|---|---|
| Electric Arc Furnace Steel (EAF): billets, wire rod, rebar (CN 7207, 7213, 7214) | 0.45 - 0.68 (direct emissions driven by high scrap charge) | 1.15 - 1.45 (punitive default route without verified technology proof) | Verified: 0.05 - 0.18 | Default: 0.84 - 1.14 | Verified: EUR 3.75 - 13.50/t | Default: EUR 63.00 - 85.50/t |
| Integrated Steel Route (BF-BOF): pig iron, slabs, hot-rolled coil (CN 7201, 7208) | 1.82 - 2.08 (with verified blast-furnace and coke-oven gas balances) | 2.45 - 2.85 (country default value with progressive markup factor) | Verified: 0.37 - 0.63 | Default: 1.00 - 1.40 | Verified: EUR 27.75 - 47.25/t | Default: EUR 75.00 - 105.00/t |
| Cement Sector: grey clinker and Portland cement (CN 2523 10 00, 2523 29 00) | 0.62 - 0.78 (accounting for mineral clinker substitutes and biomass) | 0.96 - 1.18 (default value when ISO/IEC 17025 carbonate tests are missing) | Verified: 0.04 - 0.12 | Default: 0.29 - 0.51 | Verified: EUR 3.00 - 9.00/t | Default: EUR 21.75 - 38.25/t |
| Nitrogen Fertilisers: anhydrous ammonia, urea, UAN, ammonium nitrate (CN 2814, 3102) | 1.55 - 2.05 (with catalytic N2O abatement and CEMS stack monitoring) | 2.60 - 3.25 (punitive default without verified N2O CEMS records) | Verified: 0.11 - 0.38 | Default: 1.05 - 1.70 | Verified: EUR 8.25 - 28.50/t | Default: EUR 78.75 - 127.50/t |
Protect Your EU Export Contracts from Punitive CBAM Default Values
Ekontrol engineers and lead auditors evaluate your installation's emissions accounting, build audit-proof data control systems under ISO 14001 and ISO 50001, and prepare Ukrainian manufacturers for physical CBAM verification.
Request a CBAM Diagnostic Audit with EkontrolIntegration with Ukrainian MRV Law No. 377-IX and ISO/IEC 17025 Laboratory Testing
Many large Ukrainian industrial installations already operate an approved Monitoring Plan under Law of Ukraine No. 377-IX 'On Principles of Monitoring, Reporting and Verification of Greenhouse Gas Emissions' and Cabinet of Ministers Resolutions No. 960 and No. 880, or compile corporate carbon inventories under the GHG Protocol Corporate Standard (Scope 1, Scope 2, and Scope 3). Existing national MRV documentation gives a plant roughly 65% to 70% of the primary evidence required for CBAM, but the remaining 30% to 35% structural gap regularly causes EU verifiers to reject uncorrected national reports.
The core engineering divergence comes down to system boundaries:
- Ukrainian National MRV (Law No. 377-IX) and ISO 14064-1 measure total direct emissions across the entire stationary installation boundary (boilers, furnaces, kilns, flares) as a single annual sum, without splitting fuel flows by finished product SKU and without tracking embedded emissions of purchased precursors (
EE_inp). - EU CBAM (Regulation (EU) 2023/956) requires carving the facility into discrete Production Processes tied to Annex I CN codes, stripping out energy consumed by non-CBAM workshops, calculating measurable heat transfers (
Q_imp,Q_exp) and waste gases between units, recording indirect electricity emissions, and adding the verified specific embedded emissions of every tonne of input precursor consumed.
Why CBAM Verifiers Reject Emission Factors Without ISO/IEC 17025 Laboratory Protocols
When a Ukrainian manufacturer applies the calculation-based or mass-balance methodology to prove low actual emissions, its formulas depend on physical and chemical parameters of fuels and raw materials: Net Calorific Value (NCV) and carbon content (CC) of coal, coke, natural gas, scrap, graphite electrodes, and ferroalloys, or calcium and magnesium carbonate content (CaCO3, MgCO3) in limestone, dolomite, and clay, plus free CaO in clinker.
Under Annex IV of Regulation (EU) 2023/956 and EU ETS monitoring rules, an operator may use plant-specific calculation factors (rather than conservative upper-bound IPCC default factors) only when sampling and chemical analyses are executed by testing laboratories accredited to ISO/IEC 17025 by the National Accreditation Agency of Ukraine (NAAU) or an accreditation body signatory to the European co-operation for Accreditation (EA) MLA.
During the physical site audit, the CBAM verifier inspects four metrological and laboratory pillars:
- ISO/IEC 17025 Accreditation Scope: your in-house factory lab or external contract laboratory must hold a valid ISO/IEC 17025 accreditation certificate covering the exact test standards (EN, ISO, ASTM, or harmonized DSTU methods) used to determine carbon content, ash, moisture, and calorific value for each batch.
- Documented Sampling Plans and Retained Samples: sampling from railcars, auger samplers, or conveyor belts must follow a written procedure that eliminates bias and preserves sealed reference samples.
- Metrological Calibration of Weighing and Flow Instruments: custody-transfer and internal rotary/ultrasonic gas flowmeters, hopper scales, belt weighers, truck scales, and CEMS analyzers must hold valid calibration certificates issued by ISO/IEC 17025 calibration laboratories, demonstrating a combined measurement uncertainty below the required tier threshold (
1.5%to2.5%). - Biomass Zero-Rating Proof under ISCC: if a cement kiln, dryer, or boiler co-fires solid biomass (sunflower husk pellets, wood chips, biomethane, or biogenic RDF fractions) to claim a zero emission factor (
EF_bio = 0), the fuel must satisfy RED III sustainability and greenhouse gas saving criteria verified through ISCC certification, backed by14Cbiogenic carbon fraction testing (EN ISO 21644). Without valid sustainability proof, the verifier must count 100% of the biomass carbon as fossil fuel!
Building an Audit-Proof CBAM Data Control System with ISO 14001, ISO 50001, and ISO 9001
A major surprise for exporters during their first physical CBAM verification is that the auditor checks far more than arithmetic formulas. Under ISO 14064-3 and the EU ETS Verification Regulation, the verifier must audit the operator's Data Flow Activities and Control System (risk assessment of inherent and control risks, four-eyes review, IT/ERP data integrity, and missing-data fallback procedures). When a plant relies on a standalone spreadsheet edited manually by one environmental engineer without automated reconciliation against SAP/ERP warehouse ledgers and metrological logs, the verifier classifies Control Risk as high and cannot issue an unqualified verification opinion.
Integrating three international management system standards gives Ukrainian manufacturers an auditable governance structure that satisfies both accredited CBAM verifiers and EU corporate procurement audits:
- Environmental Management System (ISO 14001): establishes organizational accountability, the register of environmental aspects and stationary emission sources, standard operating procedures for closing metering data gaps when a flowmeter or CEMS unit goes offline, internal CBAM audit schedules, and Corrective and Preventive Action (CAPA) logs.
- Energy Management System (ISO 50001): solves the hardest engineering problem in CBAM attribution, namely splitting natural gas, coal, steam, and electricity consumption across distinct production processes. Clause 6 of ISO 50001 requires identifying Significant Energy Uses (SEUs), installing line-level sub-metering, and maintaining normalized Energy Baselines (EnB), which map directly into the plant's CBAM Monitoring Methodology Documentation (MMD).
- Quality Management System (ISO 9001): governs batch identification and traceability across the supply chain (Clause 8.5.2) and control of monitoring and measuring resources (Clause 7.1.5). Embedding CBAM data requirements into ISO 9001 incoming inspection procedures forces procurement teams to collect verified precursor
SEE_ideclarations alongside mill test certificates for every incoming shipment.
Precursor Traceability (EE_inp) Across Steel, Aluminium, Cement, and Fertilisers
For downstream and midstream processors (such as hot-rolled and welded pipe mills, wire-drawing plants, fastener factories, cold-rolling mills, cement grinding plants, and complex NPK fertiliser blenders), direct on-site fuel combustion (AttrEm_g) typically accounts for only 8% to 18% of total product emissions. The remaining 82% to 92% comes from EE_inp: the embedded emissions of purchased steel billets, wire rod, hot-rolled coils, clinker, ammonia, or nitric acid.
Without batch-level traceability under ISO 9001 linking each export lot shipped to Germany or Poland back to a specific supplier heat number and its verified SEE_i report, a verifier cannot allow you to claim low-carbon precursor inputs. If EAF steel billets (0.52 t CO2e/t) and blast-furnace billets (1.98 t CO2e/t) sit in the same yard without ERP lot segregation, the auditor is legally required to apply the highest emission factor or punitive default value across the entire production run.
| CBAM Verification Requirement (Regulation (EU) 2023/956) | Primary Engineering and Accounting Evidence at the Plant | Supporting Management Standard and Clause | Typical Audit Nonconformity When Missing |
|---|---|---|---|
| Installation and Production Process Boundaries (Annex IV) | Site plan, PFD/P&ID process flow diagrams, source stream list, CN code mapping | ISO 14001 (Clauses 4.3, 6.1.2) + National MRV Monitoring Plan (Law No. 377-IX) | Including administrative heating boilers or non-CBAM machining shops inside SEE_g |
| Fuel, Measurable Heat, and Electricity Attribution (AttrEm_g) | Line-level gas, steam, and kWh sub-meters, validated enthalpy heat balances | ISO 50001 (Clause 6.3 energy review of SEUs, Clause 6.6 energy data collection plan) | Prorating the plant-wide utility gas invoice by product revenue or rough tonnage |
| Metrological Validity of Activity Data (AD) | Calibration certificates for scales and flowmeters, tier uncertainty < 1.5-2.5% | ISO 9001 (Clause 7.1.5) + ISO/IEC 17025 accredited calibration laboratories (NAAU) | Expired calibration on rotary gas meters, hopper scales, or conveyor belt weighers |
| Laboratory Proof of Calculation Factors (EF, NCV, CC, OF) | Chemical test reports for coal, coke, limestone, scrap, electrodes, ferroalloys | Testing laboratories accredited to ISO/IEC 17025 (EA MLA / NAAU) | Relying on unaccredited internal lab checks without validated sampling protocols |
| Zero-Rating of Biogenic Fuels (EF_bio = 0) | Biomass mass balance, RED III sustainability certificates, 14C fraction analysis | ISCC EU supply chain certification + ISO/IEC 17025 laboratory testing | Unverified sunflower husk pellets or wood chips treated as 100% fossil carbon |
| Precursor Batch Traceability (EE_inp) | ERP lot tracking linking supplier heat numbers and SEE_i to exported batches | ISO 9001 (Clause 8.4 supplier control, Clause 8.5.2 identification and traceability) | Commingled raw material stock; verifier forces worst-case default on all output |
| Data Flow Activities and Internal Control System (Annex VI) | Data risk matrix, four-eyes ERP reconciliation, missing-data substitution SOP | ISO 14001 (Clause 9.1 monitoring, Clause 9.2 internal audit, Clause 10.2 CAPA) | Unprotected single-user Excel file with manual overrides and no audit trail |
Engineering Synergy of ISO 14001, ISO 50001, and ISO/IEC 17025
Across Ekontrol industrial projects, manufacturers that align their Law No. 377-IX MRV Monitoring Plan with ISO 14001 data controls, ISO 50001 sub-metering, and ISO/IEC 17025 accredited laboratories cut on-site CBAM verification time by 40% to 50%. This integrated architecture protects export contracts against punitive default value markups while satisfying ESG due diligence from European lenders and OEM buyers.
Step-by-Step Engineering Roadmap for CBAM Verification Readiness with Ekontrol
Beyond the six initial sectors, on 12 June 2026 the Council of the EU approved a negotiating mandate to extend CBAM to additional downstream steel and aluminium products and tighten anti-circumvention enforcement. Manufacturers of fabricated metal goods, machinery components, and wire products sitting right outside Annex I today must build product-level carbon accounting before downstream CN codes are locked in.
To pass physical verification for the 2026 reporting year and deliver legally defensible SEE_g reports to European buyers ahead of the 2027 declaration window, the engineering and audit team at Ekontrol recommends executing a structured six-stage roadmap:
- Engineering Diagnostic of CN Codes, Process Boundaries, and Buyer Thresholds (diagnostic audit): map every exported product against Annex I of Regulation (EU) 2023/956, classify simple versus complex goods, verify your EU buyers' cumulative annual import volumes against the 50-tonne de minimis limit, and confirm their Authorized CBAM Declarant status (TARIC code Y128).
- Energy Flow Segregation and Metrological Audit (ISO 50001 and ISO 9001): isolate natural gas, coal, steam, and electricity consumption for CBAM production processes from non-CBAM workshops and space heating. Audit calibration intervals and uncertainty calculations for all gas correctors, scales, and CEMS analyzers.
- Transitioning Fuel and Raw Material Testing to ISO/IEC 17025 Laboratories: route calorific value, carbon content, and carbonate purity testing for coal, coke, ferroalloys, limestone, and clinker to laboratories accredited by NAAU, or prepare your in-house factory lab for ISO/IEC 17025 accreditation. Where solid biomass is co-fired, establish ISCC chain-of-custody certification.
- Authoring the Monitoring Methodology Documentation (MMD) and Data Control System (management system implementation): codify the mathematical formulas for
SEE_g, configure ERP batch traceability for precursor inputsEE_inpunder ISO 9001, and implement data risk controls and missing-data procedures within your ISO 14001 environmental management system. - Article 10 CBAM Registry Registration and Pre-Verification Mock Audit (audit support): register your installations in the European Commission's Operators Portal, collect verified precursor passports from upstream suppliers, and execute a full internal mock verification against the 5% materiality threshold under ISO 14064-3.
- On-Site Accredited Verification Support and Contract Integration: host the accredited verifier's physical site inspection, secure the satisfactory verification opinion, and lock verified
SEE_gclauses into your 2027 EU supply contracts.
Don't wait until an EU buyer applies punitive default values and deducts EUR 60 to EUR 90 per tonne from your contract price. Contact the Ekontrol engineering team to schedule a CBAM readiness diagnostic, align your ISO/IEC 17025 laboratory protocols, and build a certified ISO 14001 and ISO 50001 data control system.